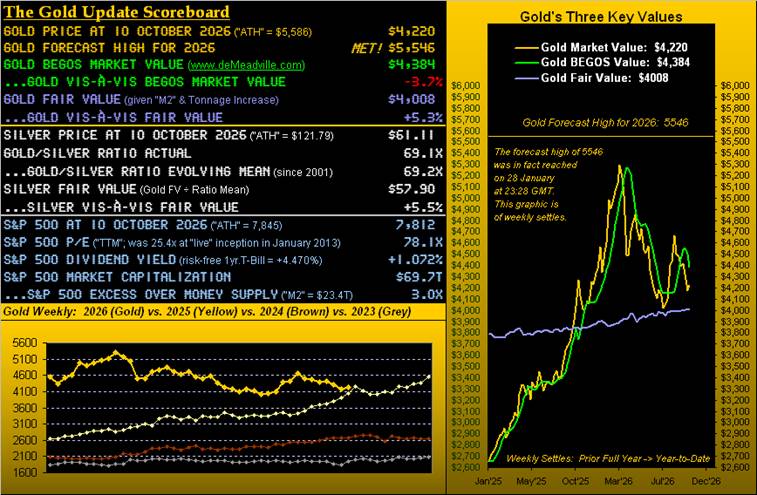
But meantime… within these recent two months of precious metals’ negativity, at least Gold and Silver managed to record respective net gains since we last met. Gold having settled yesterday (Friday) at 4220 was +1.2% (+48 points) for the week, whilst Silver closed its week at 61.11, +0.7% (+0.40 points). Regardless, Gold’s road to escaping the shivering darkness of the weekly parabolic Short trend remains quite an upside row to hoe. Let’s begin with that graphic, wherein we find Gold — despite its having regained a little ground — nonetheless posting a “lower high” for the sixth consecutive week, the dashed year-over-year regression trendline rotating to negative for the first time since mid-March 2023:
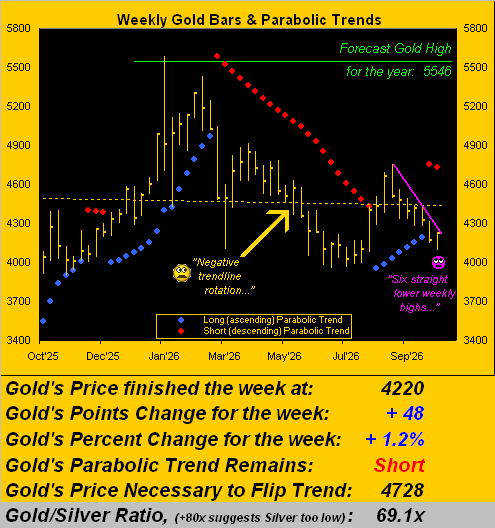
“That’s nearly a ‘lower highs’ record there, huh mmb…”
Squire, through the 1,345 trading weeks century-to-date, this is but the eighth mutually-exclusive occurrence of six or more consecutive “lower weekly highs”, the record being eight into October 2014 during the four-year stint when for Gold ’twas all going wrong.
However, the encouraging news is with Gold having closed (4220) not far off the week’s high (4234) — barring a significant down gap at Monday’s open — price this next week ought finally make a “higher high” given the expected weekly trading range now is 204 points, (the daily alone now 81 points). Either way, Gold has (yet?) to retest “The Floor” of 4000 as herein documented ad nauseam.
Notwithstanding that supportive notion for Gold, poor ol’ Sister Silver of late has been navigating her own dire strait. Whilst she’s been slipping at a greater pace than has Gold, (which is normal), she’s not been benefitting from a firmer — or at least somewhat stable — Cousin Copper. To be sure, Gold year-to-date is now -2.6% (and per the opening Scoreboard’s panel of yearly comparisons is priced almost exactly where ’twas a year ago-to-date). But: with Copper now +17.9% in 2026, it seems most untoward to find Silver -13.9%. ‘Tis as if Silver is being left too far behind even within this precious metals’ slide.
To wit, the following two-panel graphic. The upper frame encompasses the cumulative daily percentage price tracks of our Metals Triumvirate from one month ago-to-date, Copper basically being above water, with Gold and Silver sinking. The lower frame is the same stint for both the Gold/Silver ratio and Copper/Silver ratio. The rise in both ratios being stark is indicative of Silver lacking, indeed seeking, spark:
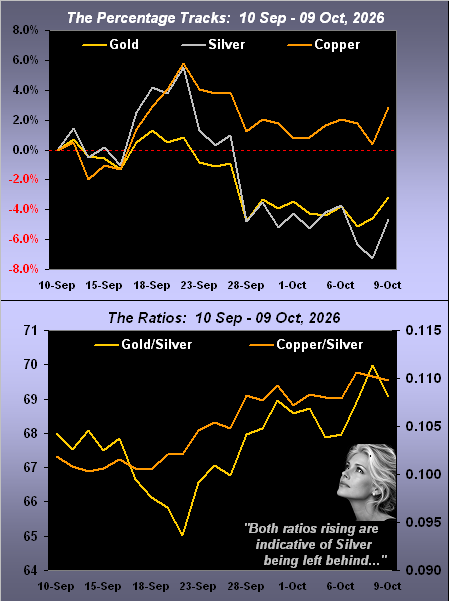
In fact, just this past Thursday, the Gold/Silver ratio exceeded 70x for the first session since 20 July, the white metal’s fallout as noted being faster than that of the yellow. Yet all that said: is Silver merely aligning with where she ought actually be? In again referencing the opening Scoreboard, the Gold/Silver ratio today at 69.1x is but one pip below its century-to-date evolving average of 69.2x. We love Sweet Sister Silver, despite her suffering more of late than Gold. But as we’ve herein quipped through the years: “Change is an Illusion, whereas Price is the Truth.” And by that maxim, Gold and Silver today are fairly priced in  “Harmony”
 –[Elton John, ’73].
“Which is why both are about the same distance above their Fair Values, right mmb?”
Absolutely correct, Squire. And as noted a week ago with respect to Gold, “The Floor” of 4000 is practically spot-on with today’s Fair Value of 4008. ‘Tis quite the catalysing confluence for considering conversion of cash into Gold, (just in case you’re scoring at home). Remember: we’re not expecting too much price adversity over the duration of this fresh weekly parabolic Short trend. Yes, yields and the Dollar are on the move just as they were from ’04 into ’06, (during which three-year stint Gold increased +53%; but we guess that shan’t be noted on CNBS). For more important than the cost of money, the amount of money needed to cover today’s massive debt and equity overvaluation doesn’t by many times even exist. “Got Gold?”
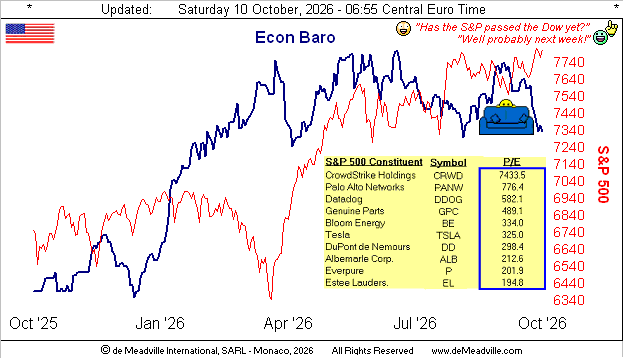
Here next we’ve the Economic Barometer. ‘Twas not a great week: with just six incoming metrics, four were worse period-over-period, the two really weak links being August’s Trade Deficit, which was worse than consensus and worse than that for July, itself revised deeper. Similarly for the month’s Consumer Credit, ’twas but half that for July, it too revised lower, and well below consensus, suggesting slowing in spending by the largest driver of the U.S. economy. At least as Q3 Earnings Season kicks into a higher gear next week, the S&P can attempt even more extreme overvaluation (understatement): all ya gotta do is beat those low-bar estimates! Here’s the Baro:
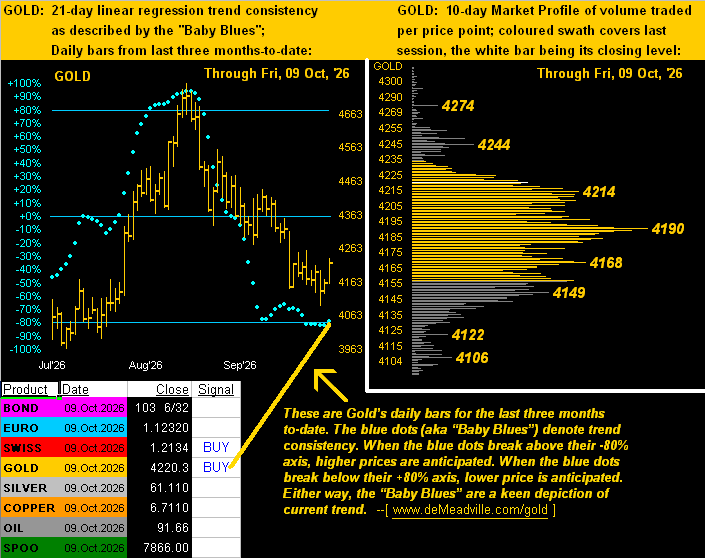
Now to a Gold positive. This is our usual two-panel graphic of Gold’s daily bars from three months ago-to-date on the left and 10-day Market Profile on the right, to which we’ve appended an internal signaling snippet that updates in the overnight work. ‘Tis specific to Friday’s finish of the “Baby Blues” having just crept above their -80% axis, the printed interpretation directly from the website. Positive as well for Gold per the Profile is the fat belly of underlying volume-dominant support, 4190 being the most commonly-traded price across the past fortnight:
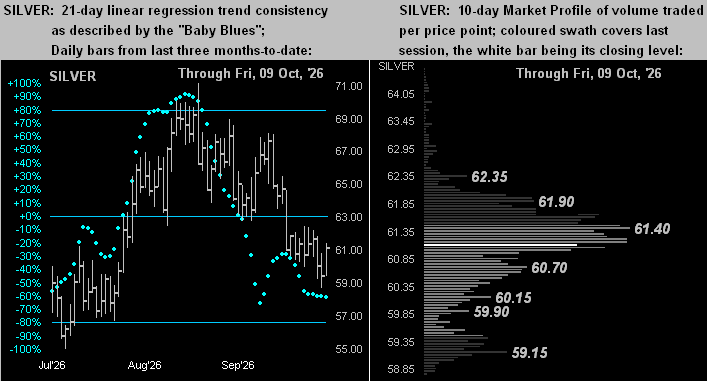
Silver’s like two-panel display has yet to find her “Baby Blues” (at left) penetrate below the key -80% axis, (not that they must reach down that far, which is for the present is a positive). By her Profile (at right), price today at 61.11 is just below volume-dominant resistance at 61.40, which of course is swiftly clearable should the precious metals further their Friday bid into the new week. “C’mon, Sister Silver!”
We thus contra-trend sense “Against All Odds” –[Columbia, ’84] that Gold and Silver are due an up week: both metals have produced but two in the past seven. Yet, Friday’s inflows saved last week, Gold’s +62-point net day’s gain (+1.5%) its best since 29 September and that for Silver of +1.68 points (+2.7%) her best since 17 September. Besides, the StateSide Executive Branch is seeing a stay of warring activities through Tuesday, 03 November (“Election Day”), a run of 17 trading days from here. And we’ve observed since the USA/IRN war get-go on 28 February (with Big Oil driving the bus): war on, Gold down; war off, Gold up!
Good grief, Squire, that really evokes a shiver in the dark… but at least they’ve “Got Gold!”
Cheers!
…m…
www.TheGoldUpdate.com
www.deMeadville.com
and now on “X”: @deMeadvillePro
deMeadville. Copyright Ⓒ 2010 - 2026. All Rights Reserved.
About the author